
Main conclusion
Visible before costs, but statistically and economically uncertain.
The equal-weighted portfolio earned an average of 0.045% per night, but the 95% interval for the difference from intraday returns included zero. Daily trading turned the result negative after 10 basis points of costs.
Study overview
The study’s scope at a glance.
Source
Daily OHLC data for 20 stocks
Study design
Prespecified universe and reserved final period
Target measure
Close-to-open minus intraday return
Comparison
Costs of 0, 2, 5 and 10 basis points
What did we want to find out?
Twenty large US stocks were selected in advance. We compared close-to-open with open-to-close returns and excluded ex-dividend dates from the primary test.
The final twelve months remained completely reserved until the final evaluation.
How was it tested?
Fixed stock universe
The group included AAPL, MSFT, NVDA, JPM, KO, XOM and WMT, among others. SPY served only as a market benchmark.
Statistical controls
Newey–West standard errors, a five-day block bootstrap and false discovery rate correction were used to guard against overstated conclusions.
Cost scenarios
Results were evaluated at 0, 2, 5 and 10 basis points per daily trade.
Key results
NVDA and KO had strong gross overnight results, but no individual stock provided convincing evidence after correction for twenty simultaneous tests.
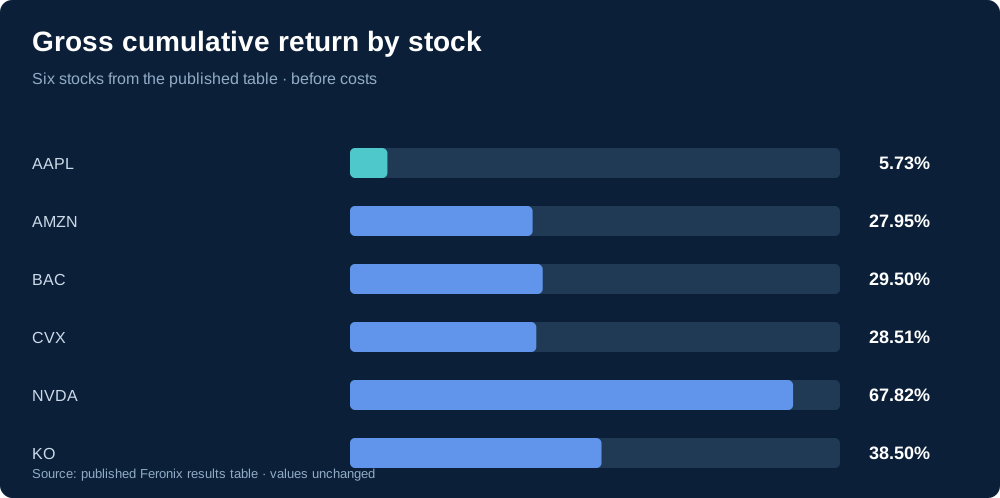
| Stock | Nights | Average | Gross cumulative return | q-value |
|---|---|---|---|---|
| AAPL | 247 | 0.03% | 5.73% | 0.912 |
| AMZN | 251 | 0.11% | 27.95% | 0.879 |
| BAC | 247 | 0.11% | 29.50% | 0.380 |
| CVX | 247 | 0.11% | 28.51% | 0.480 |
| NVDA | 247 | 0.22% | 67.82% | 0.068 |
| KO | 247 | 0.13% | 38.50% | 0.068 |
Example predictions
This study contains no individual model predictions. The table shows historical results for a fixed rule: buy an equal-weighted portfolio each evening and sell at the next opening.
| Cost per night | Expected effect | Actual conclusion |
|---|---|---|
| 0 bp | Gross effect retained | +11.83% cumulative |
| 2 bp | A small part is lost | +6.35% cumulative |
| 5 bp | A large part is lost | −1.36% cumulative |
| 10 bp | Daily trading is too expensive | −13.00% cumulative |
What should you not infer?
- The twenty companies are liquid survivors and are not representative of all stocks.
- Taxes, financing and precise execution at the opening are not included.
- An average effect does not predict whether the next night’s return will be positive.
Research findings, not investment advice. Historical relationships do not guarantee future results.